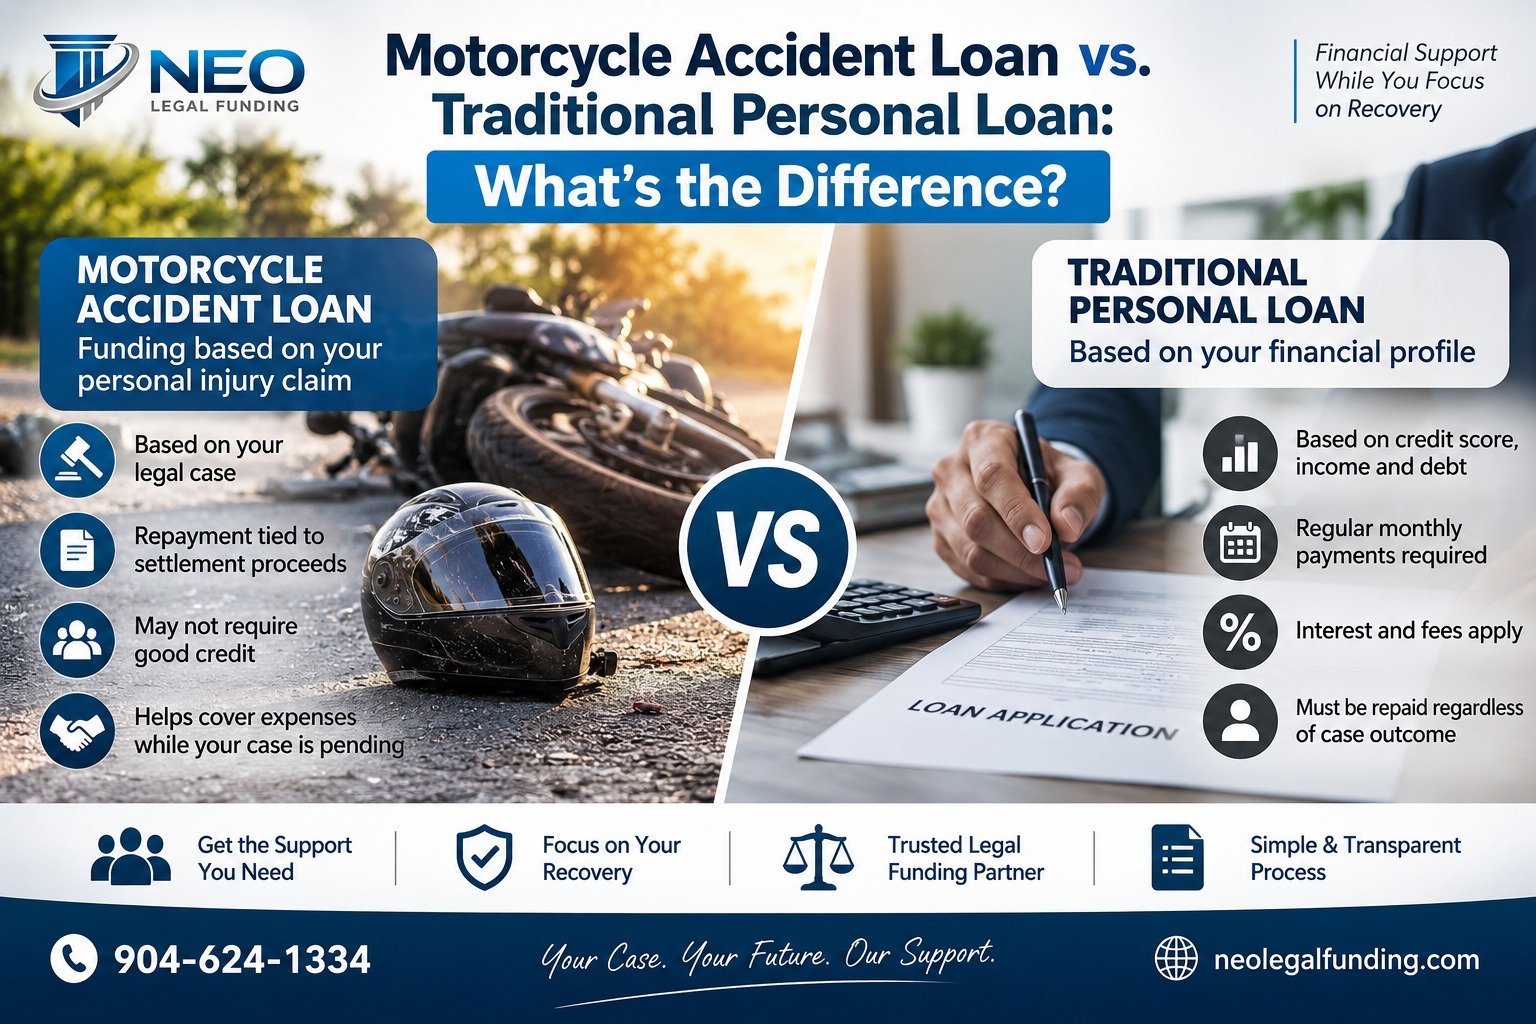
After a motorcycle accident, financial pressure can build quickly. Medical expenses, missed work, household bills, and other costs may arrive before a personal injury claim is resolved. For some injured riders, understanding the difference between a motorcycle accident loan and a traditional personal loan can help them evaluate their available financial options.
Although these terms are sometimes used interchangeably, they generally describe very different forms of financing. A traditional personal loan is based primarily on the borrower’s financial profile, while motorcycle accident settlement funding is generally connected to a pending personal injury claim.
A motorcycle accident loan is commonly used to describe pre-settlement funding or a lawsuit cash advance. In many arrangements, the funding company reviews the underlying personal injury case and provides an advance against anticipated settlement proceeds.
Traditional personal loans work differently. Banks and other conventional lenders generally consider factors such as credit history, income, existing debt, and ability to make scheduled repayments.
When a rider has an active personal injury claim, a legal funding provider may review information about the case with the applicant’s attorney.
The review may consider factors such as:
If funding is offered, the agreement determines the amount advanced, applicable fees, and repayment terms. Because agreements vary, applicants should carefully review the complete contract before accepting funding.
A traditional personal loan is normally repaid regardless of whether a separate legal claim succeeds.
For example, a lender may approve a borrower based on creditworthiness and income. The borrower then makes scheduled payments according to the loan agreement, including applicable interest and fees.
This creates a significant difference in repayment responsibility compared with many forms of non-recourse settlement funding. Traditional borrowing remains a financial obligation even if the borrower’s motorcycle accident claim is unsuccessful.
The differences can be summarized by looking at several important factors:
There is no single financing option that fits every accident victim. The appropriate choice depends on individual financial circumstances, credit profile, the status of the claim, and the terms being offered.
Before choosing a motorcycle accident loan or another financing option, consider:
Terms can vary between providers. Ask about the funding amount, fee structure, repayment conditions, additional charges, and how the balance changes if the case takes longer than expected.
Your attorney understands the details of your motorcycle accident claim and can explain legal considerations specific to your situation. Discussing the proposed agreement with your attorney before signing can help you understand how funding may interact with your case.
Settlement funding is not the only possible source of financial assistance. Depending on your circumstances, you may also consider:
NEO Legal Funding provides legal funding options for people involved in personal injury claims. The company’s website explains that its funding process involves reviewing case information and working with attorneys.
If you are considering a motorcycle accident loan, compare the terms carefully and understand the financial commitment before making a decision. Funding should be viewed as a financial option rather than a guarantee of a particular settlement or case outcome.
Conclusion: A motorcycle accident settlement advance and a traditional personal loan can provide access to funds, but they operate differently. The most important differences involve eligibility, repayment, credit considerations, and the relationship between the funding and your pending legal claim.
If you are considering funding after a motorcycle accident, review the agreement carefully and speak with your attorney about your individual circumstances. You can also contact NEO Legal Funding at 904-624-1334 or visit its website to learn more about available legal funding options.
Frequently Asked Questions
Q1. What is a motorcycle accident loan?
The term commonly refers to pre-settlement funding or a lawsuit cash advance connected to a pending motorcycle accident claim. The exact structure and repayment terms depend on the funding agreement.
Q2. How is motorcycle accident funding different from a personal loan?
A traditional personal loan generally evaluates creditworthiness, income, and repayment ability. Pre-settlement funding generally focuses more on the underlying legal claim and may be structured as non-recourse funding.
Q3. Do I need an attorney for motorcycle accident settlement funding?
Many legal funding providers require attorney involvement so the pending claim can be verified. Requirements vary by provider and case.
Q4. Do I have to make monthly payments with settlement funding?
Not necessarily. Some pre-settlement funding arrangements are repaid from settlement proceeds rather than through regular monthly payments. Always review the specific agreement before accepting funding.
Q5. What should I consider before getting a motorcycle accident loan?
Consider how much you need, the total repayment obligation, fees, repayment conditions, case status, and whether alternative financial resources may be available. Your attorney can provide case-specific legal guidance.