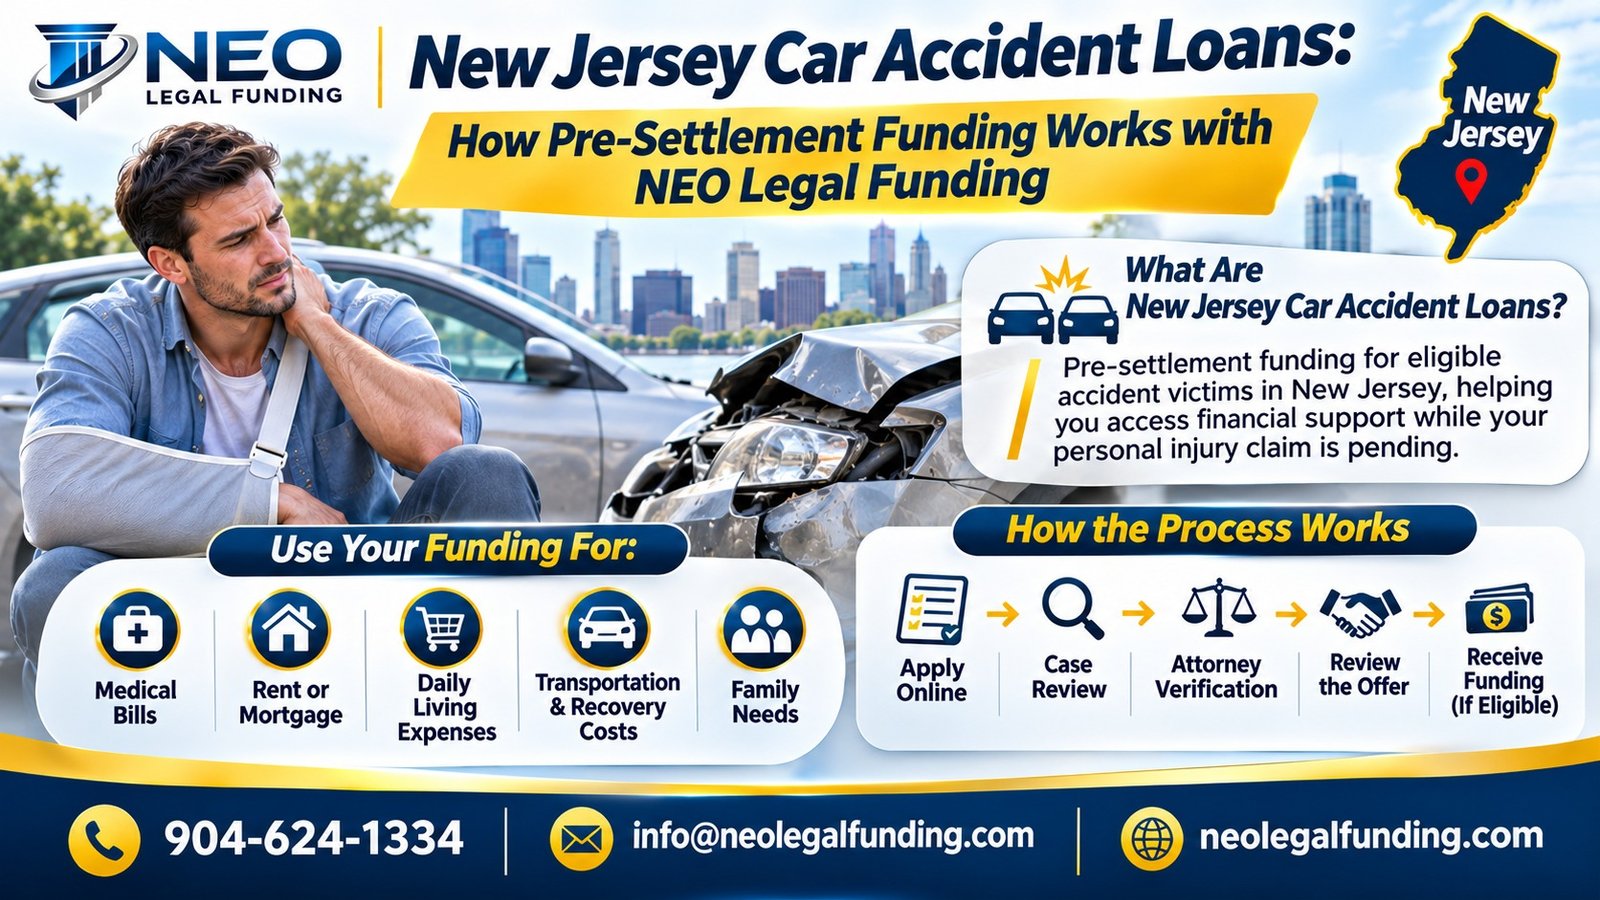
A car accident can create unexpected financial challenges, especially when injuries prevent you from working or require ongoing medical treatment. Hospital bills, rehabilitation expenses, lost income, rent, and everyday household costs can quickly become difficult to manage. These responsibilities may continue even when your personal injury claim is still being investigated or negotiated.
For injured drivers in New Jersey, New Jersey car accident loans are one option to explore when financial pressure arises before a settlement is reached. These arrangements are commonly known as car accident pre-settlement funding or lawsuit funding.
NEO Legal Funding provides funding options for eligible individuals with pending personal injury claims. Through a case-based review, qualifying applicants may be able to access financial assistance while their attorneys continue working on their cases.
If you are researching car accident loans, understanding how pre-settlement funding works, who may qualify, and what costs to consider can help you make a more informed decision.
New Jersey car accident loans generally refer to financial advances connected to pending personal injury claims. They are commonly described as pre-settlement funding because eligible plaintiffs may receive money before their legal cases reach a settlement or another resolution.
Unlike conventional personal loans, legal funding is generally evaluated based on the circumstances and potential recovery of the underlying legal claim.
A funding provider may consider:
NEO Legal Funding reviews eligible accident claims to determine whether funding may be available. Approval, funding amounts, and agreement conditions depend on individual case circumstances.
Traditional personal loans usually involve credit assessments, income verification, interest charges, and scheduled monthly payments.
Pre-settlement funding generally works differently because the financial arrangement is connected to a pending legal claim. Many legal funding agreements are structured as non-recourse arrangements, meaning repayment is generally tied to a successful recovery under the agreement.
Here are some important differences:
| Traditional Personal Loan | Car Accident Pre-Settlement Funding |
|---|---|
| Often based on credit and income | Generally evaluated using the legal claim |
| Usually requires scheduled payments | Typically does not involve regular monthly payments |
| Repayment is generally required regardless of a lawsuit | Repayment depends on the specific funding agreement |
| May be available without a pending lawsuit | Requires a qualifying legal claim |
The exact structure and costs vary. Applicants should review the written agreement rather than assuming every funding provider offers identical terms.
Financial difficulties can develop quickly after a serious accident. Even when an injured person has legal representation, the claims process may involve medical documentation, insurance investigations, negotiations, and potentially litigation.
During this period, eligible applicants may explore New Jersey car accident loans to help manage essential expenses.
Common expenses may include:
The application process for car accident funding usually involves several stages. Although requirements differ between providers, the general process may include the following steps:
Your attorney understands the circumstances of your accident and the current status of your personal injury claim. They can help provide relevant case information and explain how accepting funding could affect the money remaining from a future settlement.
Before signing an agreement, ask your attorney to review its repayment provisions and applicable charges.
Preparing relevant information can help make the application process more straightforward.
Depending on your circumstances, you may be asked for:
Not every applicant will need every document. The funding provider and your attorney can explain what information is required for your particular claim.
Before applying for car accident loans, it is important to understand how providers evaluate claims and what financial responsibilities may come with an agreement.
Although pre-settlement funding can be an option for eligible plaintiffs, approval is not automatic. Each application depends on the individual legal claim and the provider’s requirements.
Facing medical bills, lost income, and everyday expenses after a car accident in New Jersey? Pre-settlement funding may help eligible injury claimants access financial support while their case is pending. Explore your options and discuss the agreement with your attorney.
Funding is subject to case review, applicable law, and agreement terms. Review all fees and repayment conditions with your attorney.Funding providers generally consider the details of the pending personal injury claim rather than relying exclusively on the applicant’s credit history.
Common eligibility considerations may include:
Two people involved in similar accidents may receive different funding decisions because their injuries, insurance coverage, legal evidence, and claim circumstances are different.
For this reason, New Jersey car accident loans should be evaluated individually. Having an attorney or an active claim does not automatically guarantee approval.
One of the most important parts of choosing car accident loans is understanding the complete financial obligation.
The amount you receive is not necessarily the same as the amount that may eventually be owed. Depending on the agreement, charges may accumulate or change over time.
Before accepting an offer, carefully examine:
First-time applicants should consider asking these questions:
Getting clear answers can help you compare different New Jersey car accident loans based on their complete financial terms rather than just the amount offered.
If you are comparing car accident loans, take time to evaluate the provider and the agreement.
Consider the following factors:
NEO Legal Funding offers pre-settlement funding options for eligible plaintiffs with pending personal injury claims. New Jersey accident victims can contact the company to discuss their circumstances, learn about the application process, and understand what information may be required.
Contact NEO Legal Funding
Conclusion
Recovering from a car accident can be challenging when medical expenses, household bills, and other financial responsibilities continue while your legal claim is pending. New Jersey car accident loans may provide an option for eligible plaintiffs who need financial assistance before their cases are resolved.
However, pre-settlement funding is a financial commitment that deserves careful consideration. Before accepting car accident loans, compare providers, understand the total repayment obligation, and discuss the agreement with your attorney.
NEO Legal Funding can help eligible applicants explore their funding options and understand the general application process. Taking time to review your choices can help you make a more informed decision during your recovery.
Frequently Asked Questions
Q1. What are New Jersey car accident loans?
New Jersey car accident loans generally refer to pre-settlement funding provided to eligible individuals with pending personal injury claims. These arrangements may allow qualifying plaintiffs to access financial assistance before receiving compensation from their cases.
Q2. Can I apply for car accident loans with bad credit?
Pre-settlement funding is generally evaluated based on the legal claim rather than relying primarily on traditional credit scores. However, eligibility depends on the accident circumstances, available documentation, and the provider’s requirements.
Q3. Do I need an attorney to qualify for car accident funding in New Jersey?
Attorney representation and cooperation are generally required. The attorney can verify the pending claim, provide relevant information, and help review the proposed funding agreement.
Q4. Do I have to repay a car accident loan if I lose my case?
Many pre-settlement funding agreements are structured as non-recourse arrangements, meaning repayment is generally not required if there is no financial recovery. However, the specific agreement determines the repayment conditions, so applicants should confirm the terms with their attorney.